Mortgage advice for all 12 Niagara municipalities
Niagara mortgages, priced for the town you actually live in
Property tax in Fort Erie runs about 1.68%; in Niagara-on-the-Lake about 1.08%. That gap changes what you qualify for. We compare banks, monolines, Ontario credit unions and alternative lenders with the local numbers in.

Today's lowest insured 5-yr fixed
Qualifying rate 6.29% · OAC
- 3-yr fixed insured4.39%
- 5-yr fixed insurable4.39%
- 5-yr variable insured3.65%
- Credit-union 5-yr4.69%
Photo: Designecologist / Pexels
Local underwriting
Four Niagara deal-breakers the national rate sites miss
A rate is only half a mortgage. These are the local details that decide whether a Niagara file gets approved, and at what price.
Property tax swings your approval
At the same $485,000 price, Fort Erie's ~1.68% tax is about $679 a month; Grimsby's ~1.15% rate would be $465. Lenders count every dollar in your GDS ratio.
Fort Erie numbersCisterns, wells & septic
Wainfleet, West Lincoln, Pelham, Lincoln and rural NOTL homes need water potability tests, septic checks and lenders that value acreage properly.
Rural lending guideStudent rental rules
Near Brock and Niagara College, lenders want legal bedrooms, proper leases and municipal licensing before they count the rent.
Student rental guideRenewal without re-qualifying
A straight switch at renewal no longer needs the stress test. Households renewing off 2020–2021 rates can shop every lender, not just their own.
Renewal guideMortgage pathways
Start from your situation
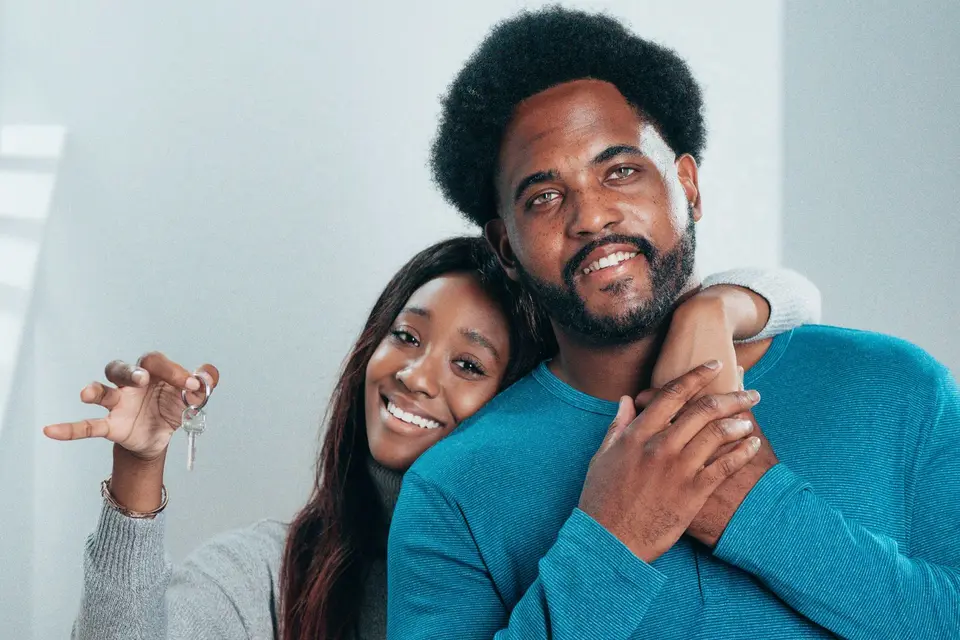
Buying & first-time buyers
5% down on the first $500,000, 30-year insured amortization for first homes and new builds, $4,000 LTT refund and no municipal LTT.
Explore
Renewal or rate switch
Start 120–150 days out. Compare a straight switch against your lender's offer and see what breaking early would really cost.
Explore
Debt consolidation & equity
Roll 19.99% card and car balances into a refinance up to 80% of your home's value, and see the monthly cash flow it frees.
Explore
Self-employed & alternative
T1 Generals, stated-income and bank-statement programs, B-lenders with a 1–2 year exit plan back to prime rates.
Explore
Investors & student housing
DCR versus 50% rental add-back, legal bedrooms, duplex conversions and the secondary-suite refinance rule.
Explore
Rural, vineyard & cottage
Hobby farms, NEC-area homes, Crystal Beach cottages and licensed short-term rentals with the lenders that finance them.
Explore12-municipality explorer
Prices, property tax and minimum down, town by town
Benchmark prices and approximate tax rates for every Niagara municipality, with the Ontario land transfer tax at each price. Pick a town for its full local guide.
| Municipality | Benchmark price | Approx. tax rate | Tax / month | Minimum down | Ontario LTT |
|---|---|---|---|---|---|
| St. Catharines | $530,000 | ~1.26% | $556 | $28,000 | $7,075 |
| Niagara Falls | $565,000 | ~1.22% | $574 | $31,500 | $7,775 |
| Welland | $485,000 | ~1.32% | $534 | $24,250 | $6,175 |
| Grimsby | $725,000 | ~1.15% | $695 | $47,500 | $10,975 |
| Fort Erie | $485,000 | ~1.68% | $679 | $24,250 | $6,175 |
| Lincoln (Beamsville, Vineland, Jordan) | $695,000 | ~1.18% | $683 | $44,500 | $10,375 |
| Thorold | $525,000 | ~1.30% | $569 | $27,500 | $6,975 |
| Niagara-on-the-Lake | $865,000 | ~1.08% | $779 | $61,500 | $13,775 |
| Pelham (Fonthill, Fenwick) | $795,000 | ~1.21% | $802 | $54,500 | $12,375 |
| Port Colborne | $475,000 | ~1.48% | $586 | $23,750 | $5,975 |
| West Lincoln (Smithville) | $660,000 | ~1.19% | $654 | $41,000 | $9,675 |
| Wainfleet | $635,000 | ~1.28% | $677 | $38,500 | $9,175 |
Benchmark prices from Niagara Association of REALTORS® HPI composites (rounded); tax rates are approximate effective residential rates; confirm with the municipality. No municipal land transfer tax applies anywhere in Niagara.
Rates & lender tiers
Transparent rates, and who actually pays the broker
| Rate tier | 3-yr fixed | 5-yr fixed | 5-yr variable |
|---|---|---|---|
| High-ratio insuredUnder 20% down, CMHC / Sagen / Canada Guaranty | 4.39% | 4.29% | 3.65% |
| Insurable20%+ down, purchase or switch, up to $1.5M | 4.49% | 4.39% | 3.75% |
| Uninsured (conventional)Refinances, $1.5M+, most rentals | 4.64% | 4.54% | 3.95% |
| Ontario credit-union tierProvincially regulated lenders | 4.74% | 4.69% | 4.10% |
| Alternative "B" lender1–2 year terms typical, fees disclosed | 5.49%–6.99% | — | Prime + 0.50–2.00 |
| Private / MIC1-year, interest-only, fees disclosed | 8.99%–12.99% | — | — |
Indicative benchmark rates for qualified borrowers, OAC. Rates change daily and depend on credit, property, amortization and loan size. Big-6 posted 5-year fixed for penalty math: 6.09%. Not a commitment to lend.
| Lender tier | Best for | Typical 5-yr rate | Fees to you |
|---|---|---|---|
| Prime "A" banks & monolines | Salaried and established self-employed borrowers, 680+ credit | 4.29%–4.54% | None: the lender pays the brokerage (typically 80–110 bps) |
| Ontario credit unions | Ratios over 39/44, rural homes, files outside federal stress-test rules | ~4.69% | Usually none |
| Alternative "B" lenders | Bruised credit, stated income, recent self-employment | 5.49%–6.99% | Lender fee ~1% plus a disclosed broker fee |
| Private lenders & MICs | Bridge loans, construction, proposals, fast equity | 8.99%–12.99% | Lender and broker fees, ~1.5%–3%, disclosed in writing |
How it works
From a number to a rate hold in three steps
Run the Niagara numbers
Choose your municipality and price. See payment, property tax, CMHC premium, the 8% PST on it, land transfer tax and cash to close.
Send them to an advisor
One click attaches your calculation. A licensed advisor checks it against A-lenders, credit unions and alternative lenders.
Hold a rate, then close
Pre-approve with a rate hold of up to 120 days, compare written offers, and close with a Niagara real estate lawyer.
Niagara mortgage questions
How much do I need for a down payment on a Niagara home?
5% of the first $500,000 and 10% of the portion above it, up to $1.5 million. On St. Catharines' benchmark of about $530,000 that is $28,000; on a $485,000 Welland or Fort Erie home it is $24,250. At $1.5 million and above, 20% is required.
Is there a municipal land transfer tax in Niagara?
No. Only Toronto charges a municipal land transfer tax in Ontario. Niagara buyers pay the provincial Ontario LTT only, for example $7,075 on a $530,000 home, and first-time buyers can get up to $4,000 of it refunded.
Why does my town's property tax rate matter for my mortgage?
Lenders add property tax to your Gross Debt Service (GDS) ratio, capped at 39% on insured mortgages. At about 1.68%, Fort Erie's rate adds roughly $214 a month more than Grimsby's 1.15% on the same $485,000 house, which lowers the mortgage you qualify for.
Do I pay a fee to use a mortgage broker in Niagara?
Not on prime files: banks, monolines and credit unions pay the brokerage a finder's fee, typically 80–110 basis points of the loan. Alternative and private mortgages usually carry a broker fee, which is disclosed to you in writing before you commit.
Do I have to pass the stress test again at renewal?
Not if you do a straight switch: same balance and same remaining amortization moved to a new lender. Since November 21, 2024 that applies to uninsured mortgages too. Adding money or extending the amortization means qualifying again at the higher of 5.25% or your rate plus 2%.
Pre-approval & rate review
Get your Niagara mortgage numbers checked
Tell us where you are buying or what you owe. We reply by email, usually within one business day, with options from across the lender tiers.
- A licensed advisor reviews your numbers against A-lenders, Ontario credit unions and alternative lenders.
- Rate holds of up to 120 days on purchases and renewals (lender-dependent).
- On prime files the lender pays the brokerage, so there is no fee to you; any fee on alternative or private files is disclosed in writing first.
- Nothing goes to a lender or credit bureau until you say so.
Prefer email? Write to hello@mortgageniagara.com.